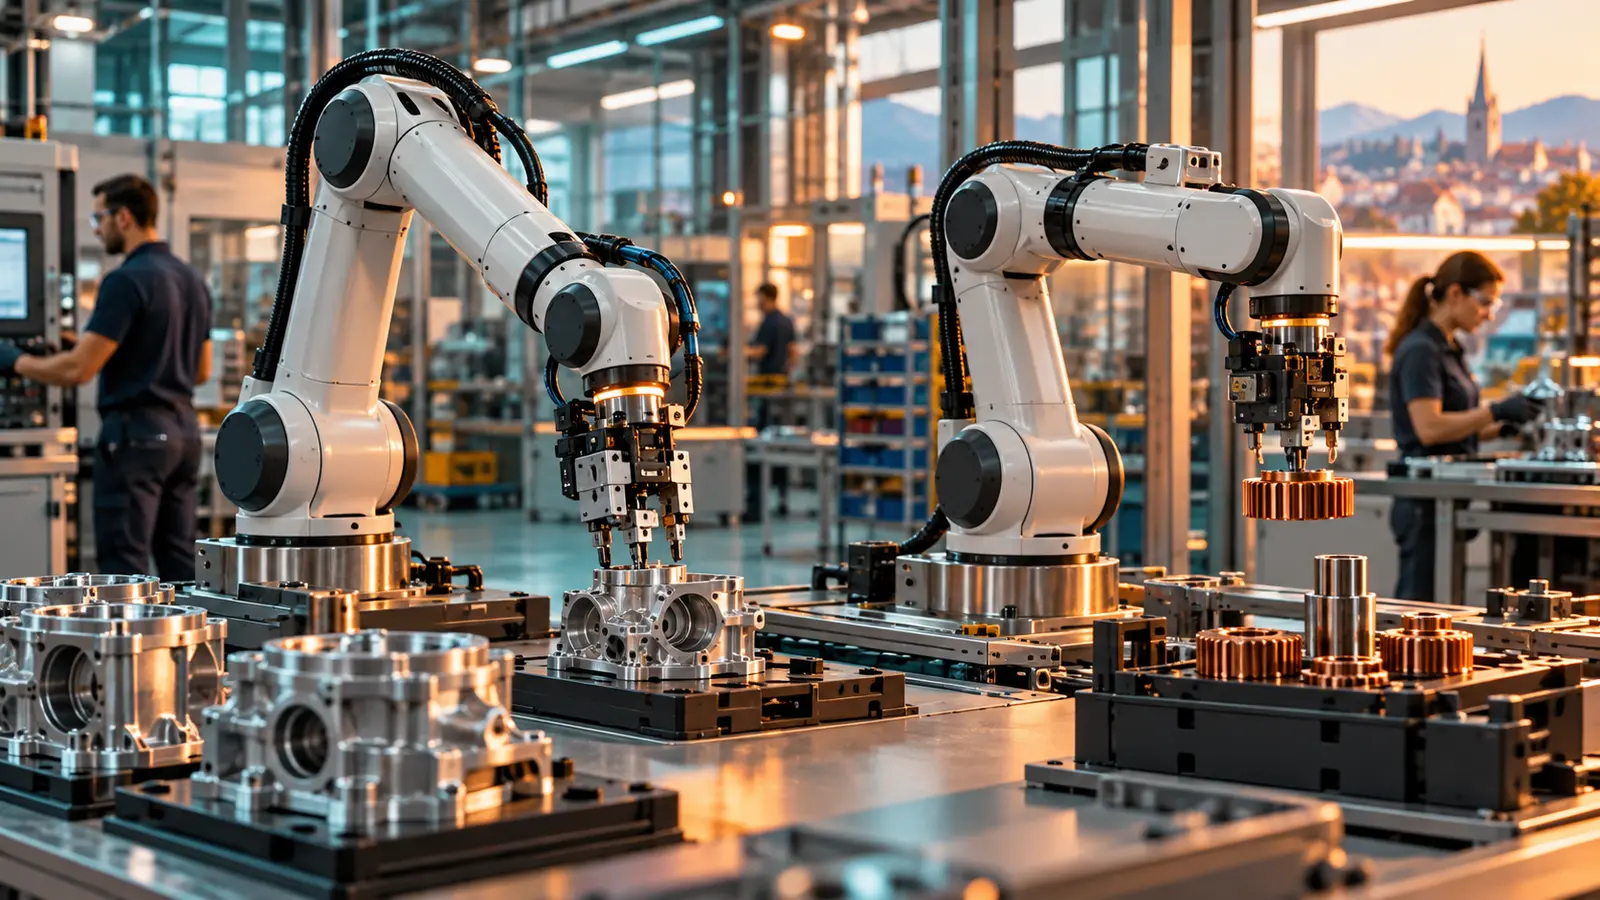
The official release sets Alfie’s commercial timetable and makes US expansion a priority. Reuters and The Wall Street Journal corroborate the billion-dollar threshold. The valuation comes from a financial transaction; it is neither revenue nor an equivalent sum paid into the company. That distinction matters. A transaction may combine new shares with existing ones. It reflects investor expectations, but does not reveal the number of installations, a robot’s availability or its profitability for a customer.
The ambition: adapt to less repetitive tasks
RobCo describes Alfie as an industrial system combining perception, reasoning and execution. This is the manufacturer’s description. A launch planned for March 2027 must not be presented as general availability in October 2026.
The real test is ordinary factory variation. A different part or production rate can change a task’s difficulty. A valuable tool must remain useful when conditions depart from the demonstration, while staying supervisable and compatible with safety requirements.
Subscription shifts the cost question
The official site promotes robotics as a service. For a company, this could move part of the purchase expense into recurring payments. It does not remove costs or risks.
Value will depend on what is actually included: integration, maintenance, support, updates and availability. The effect on workers will also depend on job design and acquired skills. No universal quantified gain follows from the announced valuation.
Conclusion
RobCo has new backing for its development. Factories should judge Alfie on documented performance and the complete service. To understand the announcement’s effect, watch the work performed after launch, not only the value assigned to the company beforehand.
Comments 0
Be the first to comment on this article.